Executive Contents
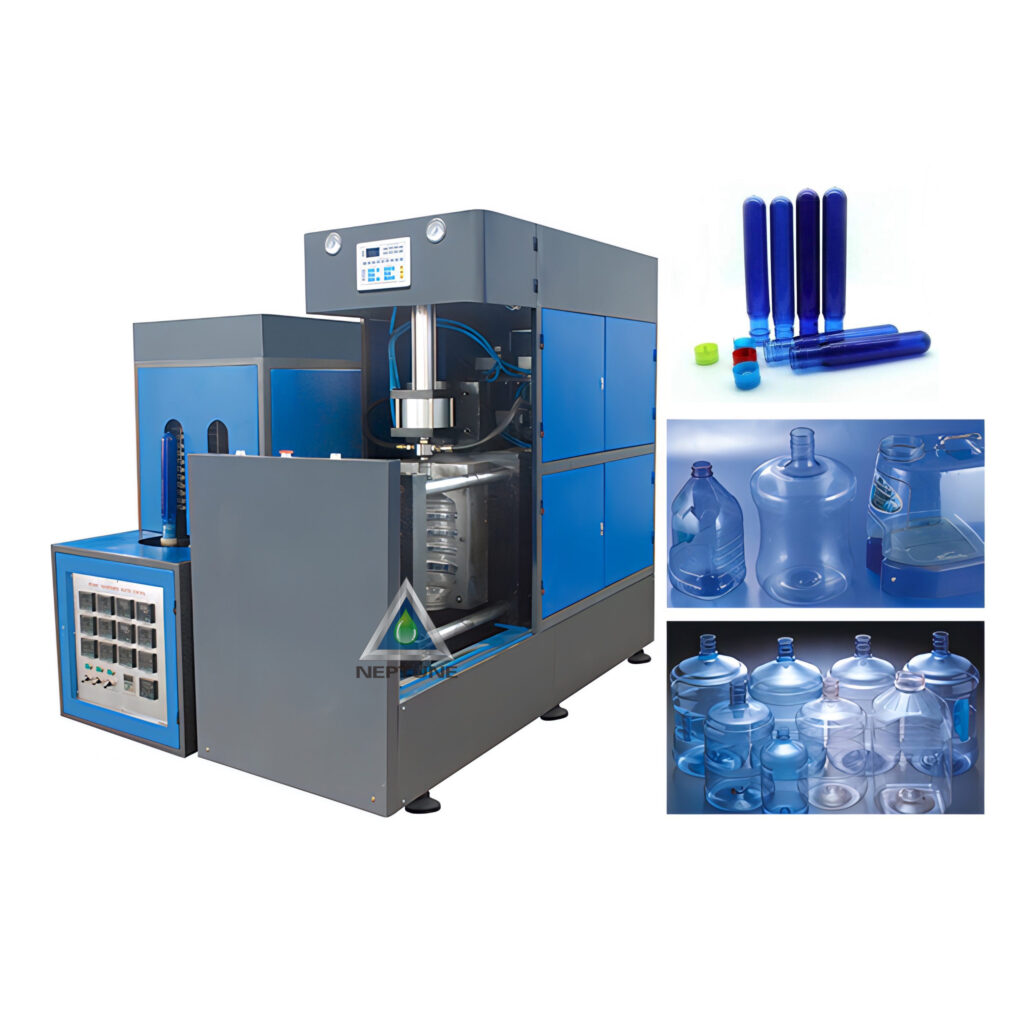
Executive Market Briefing: Plastic Bottle Making Machine
Executive Market Briefing – Plastic Bottle Making Machines (2025)
BLUF
Global demand for PET bottle blowing machines is expanding at a 4.8% CAGR toward a USD 3.05 Bn equipment market by 2030, while the broader PET blow-molding segment is on a USD 10.3 Bn → USD 14.2 Bn trajectory (2024-34). China supplies 68% of world unit volume at index 100, Germany delivers 13% at index 220, and the USA holds 9% at index 250; upgrading to servo-hydraulic or all-electric platforms now locks in 12-18% energy savings and 8-10% cycle-time gains before carbon-border tariffs tighten in the EU (2026) and the US (2027).
Demand & Growth Vector
The installed base is aging: 42% of lines in beverage and 38% in home/personal care were commissioned before 2015. Rising post-consumer r-PET mandates (EU: 50% by 2025, India: 60% by 2027) are forcing converters to retool for higher intrinsic-viscosity variability and 10-15% faster cycle times. Annual throughput demand for sub-5 L bottles is forecast to rise 5.3% through 2030, driven by CSD, edible oil and functional water SKUs. Consequently, small-scale semi-automatic units (≤6 k bph) are growing at 6.2%—double the rate of large rotary machines—as craft beverage and regional dairy players localize production.
Supply-Hub Economics
Chinese OEMs (Guangzhou Tech-Long, Jiangsu Newamstar, Zhangjiagang King Machine) deliver rotary blowers at USD 50k-80k per 4-k bph module, 20-week lead time, 2-year warranty. German makers (Krones, KHS, SIPA) price equivalent output at USD 180k-220k, 30-week lead, 5-year warranty, 30% lower energy draw and full Industry 4.0 retrofit. US builders (Sidel-Atlanta, Mag-Plastic) focus on 12-k bph+ hybrids at USD 250k-320k, qualifying for 30% IRA capital credit when >50% domestic content is proven. Total cost of ownership (TCO) parity between China and Germany occurs at 6.8 years assuming EU energy prices; in North America, domestic sourcing reaches parity at 4.5 years once logistics and tariff avoidance are counted.
Strategic Value of 2025 Upgrade Window
Energy: EU electricity prices averaged USD 0.22 kWh in 2024; each 1 k bph saved equates to USD 11k annual power avoidance at German efficiency levels. Carbon: CBAM reporting starts 2026; every tonne of CO₂e not emitted saves USD 85 in future levies. Resin: New servo stretch-blow platforms cut preform weight by 0.3 g on 500 mL bottles; at PET USD 1.30 kg, a 12-k bph line saves USD 1.1 M per annum. Availability: Post-pandemic component shortages have eased—ball-bearing and valve lead times down from 40 to 12 weeks—but geopolitical risk is rising; securing 2025 slots locks OEM price books before 8-10% steel and aluminum inflation expected 2026. Finance: US and EU lenders are offering 3.9-4.2% green-asset loans for equipment that demonstrates ≥15% energy reduction versus baseline, shaving 200-300 bps off traditional IRR hurdles.
Comparative Supply Matrix (2025)
| Metric | China Tier-1 | Germany Tier-1 | USA Tier-1 |
|---|---|---|---|
| Output range (bph) | 2k–14k | 4k–40k | 6k–48k |
| Price index (4k bph) | 100 | 220 | 250 |
| Energy index (kWh/1k bottles) | 100 | 70 | 68 |
| Lead time (weeks) | 18–22 | 26–32 | 24–30 |
| Warranty (years) | 2 | 5 | 5 |
| r-PET ready (>30%) | Optional | Standard | Standard |
| Digital twin / IoT | Add-on | Integrated | Integrated |
| TCO breakeven vs. China (EU energy) | — | 6.8 yr | 7.5 yr |
| TCO breakeven vs. China (US energy) | — | 9.2 yr | 4.5 yr |
| Carbon tariff exposure (2030) | High | Low | Low |
Decision Implication
CFOs with CAPEX ceilings under USD 1 M can secure quick-payback semi-automatic modules from China, but should embed energy-use escalation clauses to offset future EU/US carbon fees. Global bottlers targeting 2 B units/yr or more gain USD 3-5 M annual net benefit by migrating to German or US all-electric platforms now, while green-loan rates and OEM slot availability remain favorable.
Global Supply Tier Matrix: Sourcing Plastic Bottle Making Machine
Global Supply Tier Matrix: Plastic Bottle Making Machines
Executive Snapshot
Tier-1 (EU/USA/Japan) delivers 99.5 % uptime, 24-month warranties and full FDA/EFSA documentation at 3-4× the asset intensity of Chinese Tier-2 equivalents. Tier-2 (China/India) cuts CapEx by 55-65 % but injects 8-15 pp of additional compliance volatility and 4-8 weeks of port-side delay. Tier-3 (Southeast Asia, Turkey, Eastern Europe) is a tactical spot-buy arena—acceptable for capacity surges, suicidal for long-term brand risk.
Regional Trade-off Table (2024 benchmark, 4-cavity, 10 k bph PET rotary blower)
| Region | Tech Level (max output / kWh) | Cost Index (USA = 100) | Lead Time FOB (weeks) | Compliance Risk Score* |
|---|---|---|---|---|
| Germany / Italy | 1 050 bph / 32 kWh | 185–210 | 20–24 | 5 |
| USA / Japan | 980 bph / 34 kWh | 100 (baseline) | 16–20 | 5 |
| South Korea | 920 bph / 36 kWh | 90–95 | 14–18 | 10 |
| China East Coast | 900 bph / 38 kWh | 42–48 | 10–14 | 35 |
| China Interior | 820 bph / 40 kWh | 36–40 | 12–16 | 45 |
| India | 800 bph / 42 kWh | 38–44 | 14–18 | 40 |
| Turkey | 780 bph / 43 kWh | 50–55 | 8–12 | 30 |
| Vietnam / Thailand | 750 bph / 45 kWh | 46–52 | 10–14 | 50 |
*Compliance Risk Score: weighted average of FDA/EFSA traceability, UL/CE file validity, vendor audit red-flags, forced-labor exposure, resin contamination recalls (0 = negligible, 100 = shipment rejection probability >8 %).
CapEx vs. TCO Reality
A EU-built rotary stretch-blow molder priced at USD 1.4–1.6 M delivers 25 % energy savings and <1 % scrap versus a USD 0.55–0.65 M Chinese unit. At 200 M bottles/year and USD 0.10/kWh, the energy delta alone recovers the premium in 28–32 months; add avoided recall cost (average USD 0.9 M per contamination event) and the EU machine pays back in <18 months for any CPG with >0.5 % margin erosion risk.
Risk-Adjusted Sourcing Playbook
North America/EU Plants Feeding Retail Chains: Dual-source 80 % from Tier-1, 20 % from South Korea for surge flex; lock 5-year service contracts with local OEM tech centers to guarantee <48 hr MTTR.
Emerging Market Hubs Focused on Value Brands: Anchor 60 % of capacity on Tier-2 Chinese equipment vetted through on-site pilot runs and resin traceability audits; retain 40 % Tier-1 capacity for private-label export orders that require retailer audit certificates.
Tactical Spot Buys (promotional runs, short SKU life): Deploy Tier-3 vendors only under LC 90-day terms, accompanied by third-party pre-shipment inspection and contingent cargo insurance; cap single-vendor exposure at 5 % of annual bottle volume to contain recall fallout.
Financial Analysis: TCO & ROI Modeling
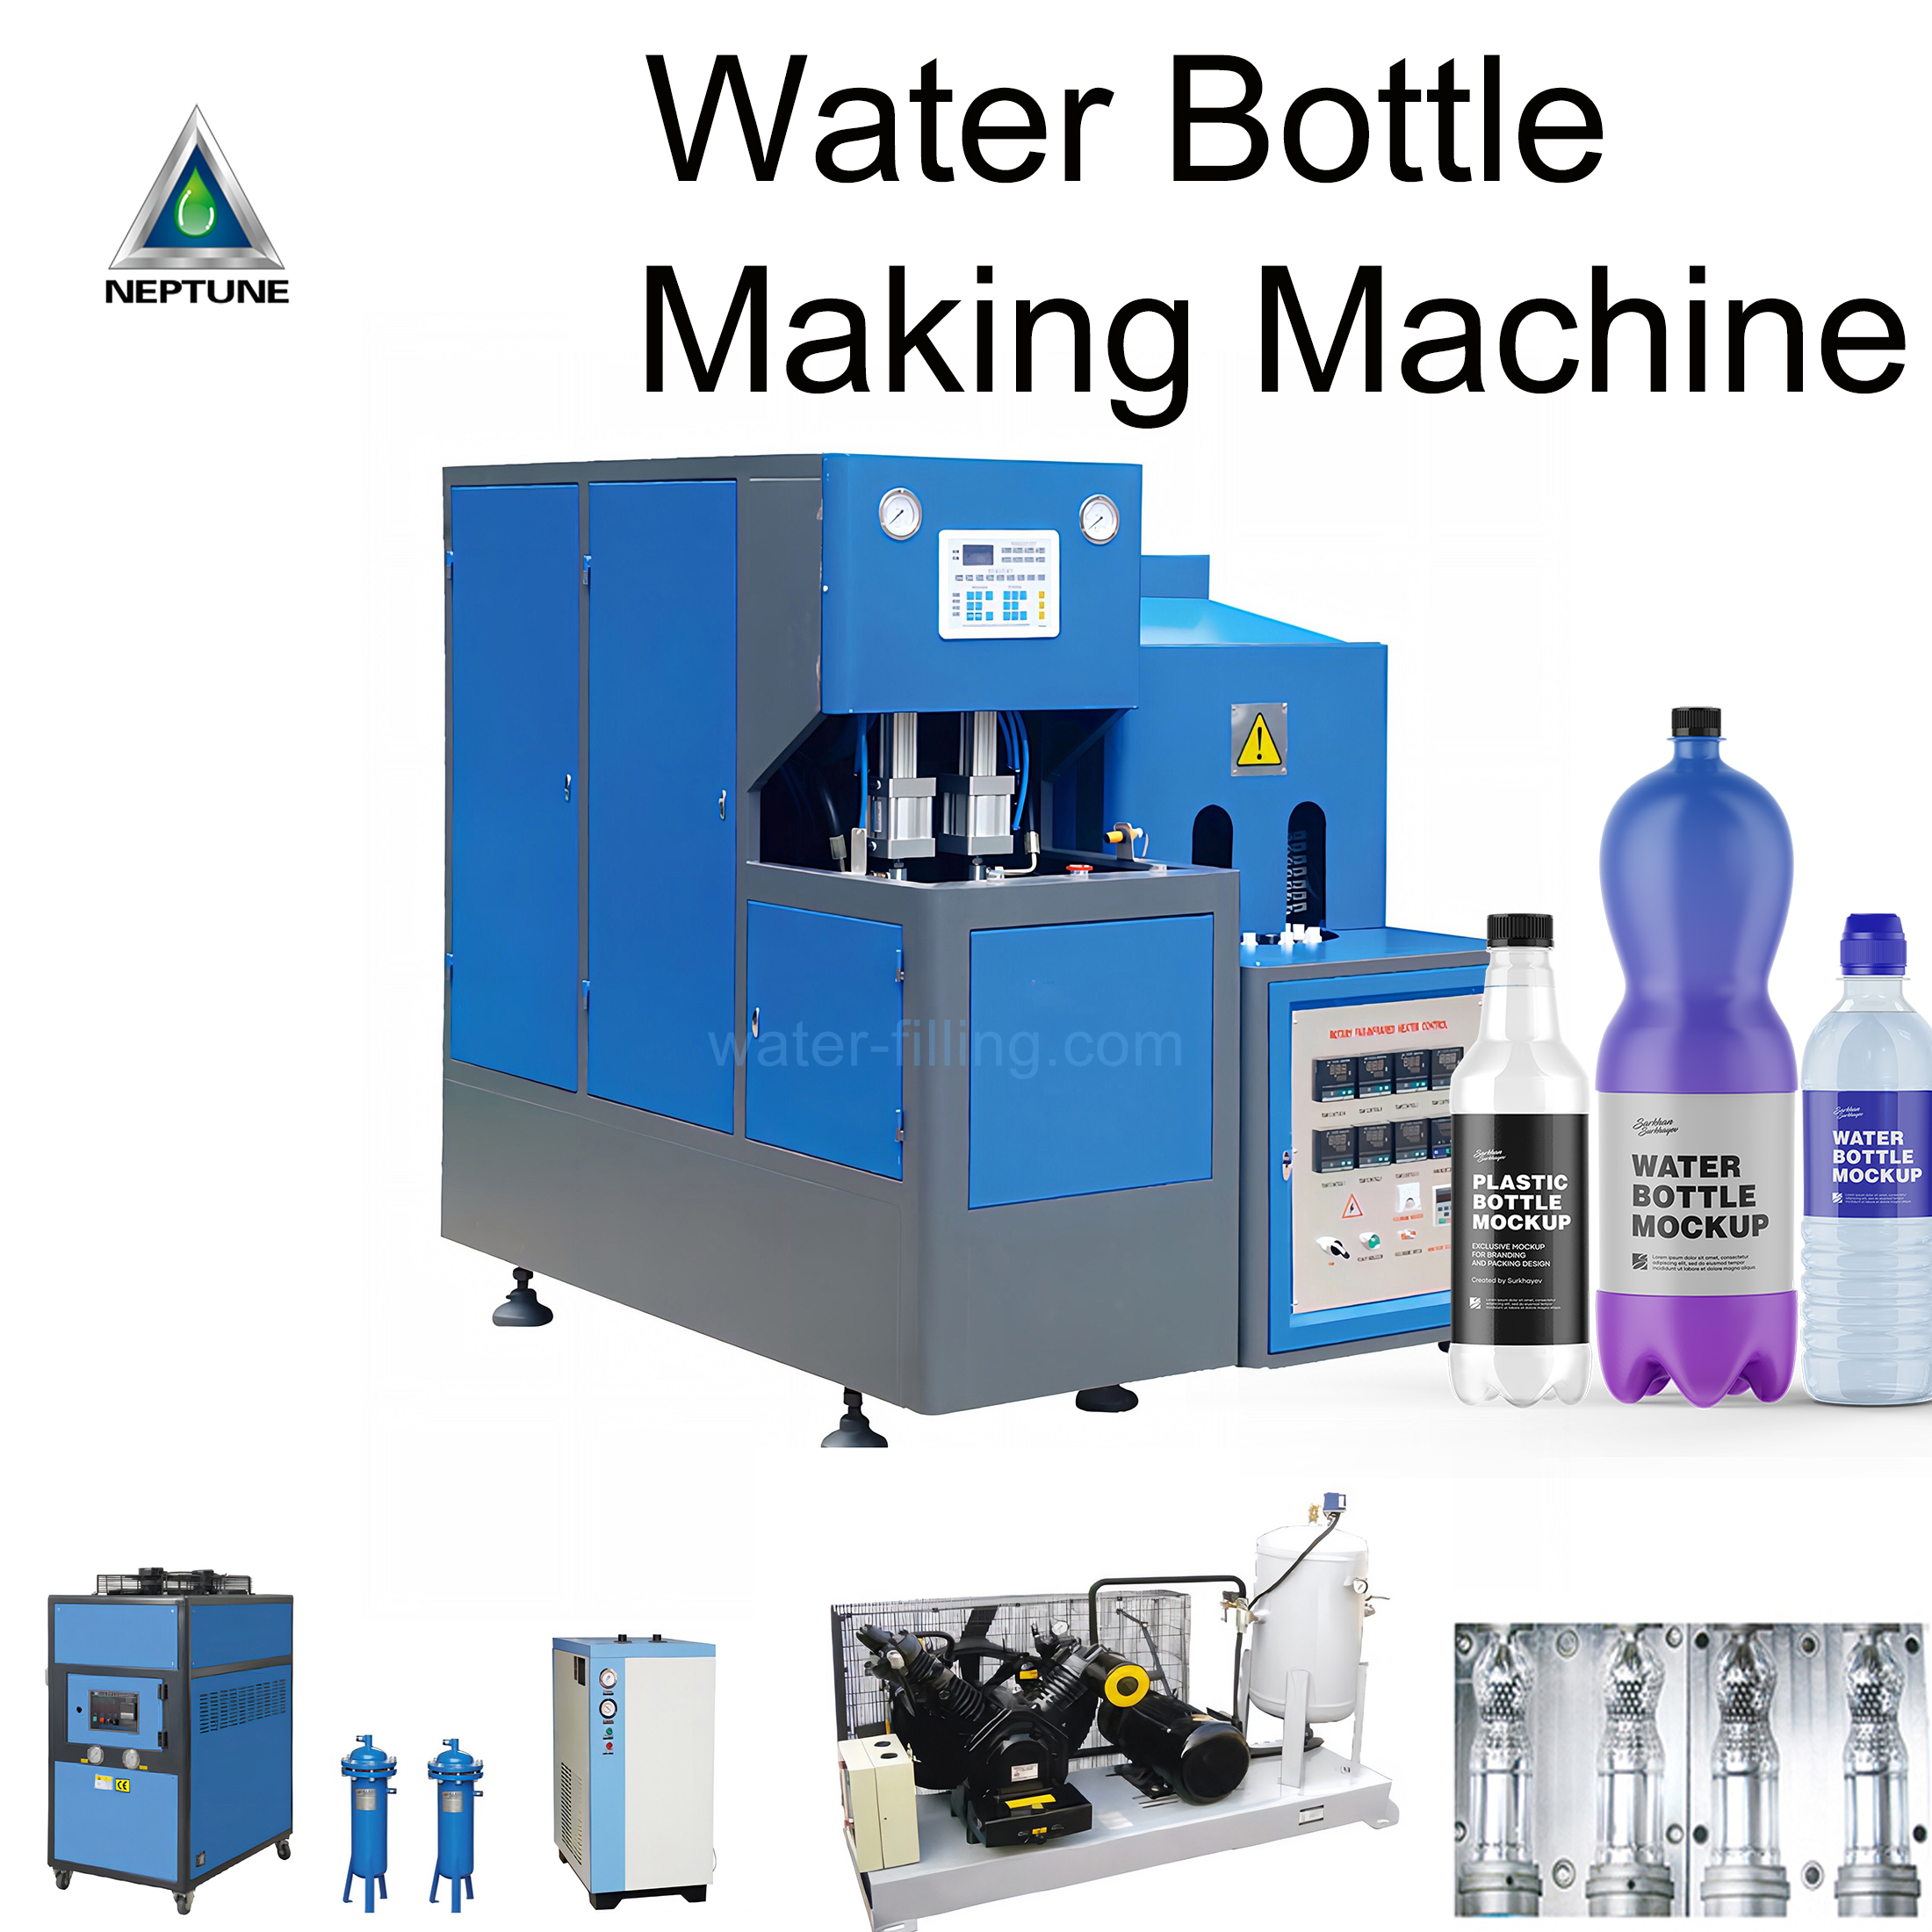
Total Cost of Ownership (TCO) & Financial Modeling
The headline FOB price for a small-scale PET blow-molding line—typically $36k–$100k for 2,000–6,000 bph semi-automatic units and $110k–$180k for 8,000–12,000 bph fully servo-electric models—represents only 55–65 % of the cash that will actually leave the company over a five-year holding period. The remaining 35–45 % is consumed by four post-procurement value leaks: energy, maintenance labor, spare-parts logistics, and resale value erosion. Ignoring these variables turns a 24-month payback into 40+ months and erodes IRR by 6–8 pp.
Energy Efficiency: The 8 % Cash Drain
Electricity is the single largest operating cost after resin. A 10 cavitation, 12,000 bph rotary machine rated at 65 kW will draw ~380 MWh per year at 85 % utilization; at an average industrial tariff of $0.11 kWh that equals $42 k p.a. A servo-driven model with regenerative blower and IR oven cuts nameplate power by 18–22 %, saving $7.5 k–$9 k annually. Over five years the present value of those savings (8 % WACC) is $30 k–$36 k—enough to justify a $25 k capital premium for the high-efficiency variant. Carbon-price scenarios (EU ETS forward curve +7 % YoY) raise the value of each saved kWh to $0.13–$0.15 by 2028, widening the competitive gap between Tier-1 (Krones, SIPA) and low-cost Asian OEMs whose specific energy remains ≥0.33 kWh per 1,000 bottles.
Maintenance Labor & Spare-Parts Logistics
Mean Time Between Failure (MTBF) for Chinese semi-automatic frames averages 380–420 operating hours versus 1,100–1,300 h for European servo platforms. Each unplanned stop costs 2–3 labor hours plus 100–150 USD in emergency airfreight for valves, cylinders, or infrared lamps. Annualized, maintenance labor for a low-tier asset runs 4.2 % of FOB price versus 1.8 % for a premium asset. Spare-parts logistics add another 2.5–3.0 % because Chinese suppliers consolidate shipments, resulting in 30–35 days average lead time versus 5–7 days from EU/US part hubs. Carrying a recommended 1.5 % of FOB value in safety stock ties up an extra $1.5 k–$2.7 k in working capital per line.
Resale Value & Obsolescence Risk
Secondary-market data (2020-2023) show that five-year-old European machines retain 42–48 % of original invoice value if maintenance logs are complete. Comparable Chinese assets trade at 18–22 % of FOB, largely because controller software and pneumatic components are already unsupported. The 25 pp delta on a $150 k asset equals $37 k of hidden depreciation—equivalent to 0.8 c per bottle over a 500 m-unit production life. Electrification trends (EU ESPR, California SB 54) will accelerate residual-value decay for pneumatic-heavy models; expect an additional –3 pp year-over-year after 2026.
Hidden Cash Outflow Table
| Cost Category | Semi-Automatic Chinese (FOB $50 k) | Servo-Electric EU (FOB $150 k) | Notes / Drivers |
|---|---|---|---|
| Installation & rigging | 8 % | 6 % | Foundation, air, water, 3-phase |
| Commissioning & FAT travel | 3 % | 2 % | Flights, hotels, 5–7 technician days |
| Operator training (on-site) | 2 % | 1 % | 3 days vs 1 day due to simpler HMI |
| Import duties & brokerage | 7 % | 0 % | HS-847730 Chinese origin 7 % into US/EU |
| First-year spares package | 4 % | 2 % | Mandatory kits to honor warranty |
| Total Hidden Up-Front | 24 % | 11 % | Cash impact before first bottle |
Financial Model Output
Overlaying the above on a 5-year, 8 % discount cash-flow model yields a TCO range of $89 k–$110 k for the $50 k Chinese unit and $205 k–$230 k for the $150 k EU line. Yet the higher-capacity servo platform delivers 1.8 bn bottles versus 0.9 bn, dropping cost per 1,000 bottles to $0.115 versus $0.122. More critically, the EU asset’s residual value adds $63 k exit cash, shrinking net TCO to $0.079 per 1,000 bottles—3.6 c lower than the “cheap” alternative. For CFOs the takeaway is unambiguous: purchase price is a minority shareholder in the TCO equation; energy, uptime, and resale value dictate IRR and EVA.
Risk Mitigation: Compliance Standards (USA/EU)
Critical Compliance & Safety Standards (Risk Mitigation)
Importing a plastic bottle making machine into the United States or the European Union without documented conformity to the standards below exposes the buyer to product seizures, forced recalls, seven-figure fines and, in the event of worker injury, criminal liability. The cost of retrofitting a non-compliant line averages $50k–$120k plus 6–10 weeks of lost output—more than the original FOB price of most Asian-sourced semi-automatic units. Executives should therefore treat certification evidence as a hard gate in supplier qualification, not a post-shipment formality.
United States – Mandatory Third-Party Marks
Under OSHA 29 CFR 1910 regulations and the federal Occupational Safety and Health Act, every electrically powered bottle blow-molding line is classified as industrial machinery; it must carry a NRTL (Nationally Recognized Testing Laboratory) mark—most commonly UL 508A for the industrial control panel and UL 73 for the overall machine. The absence of a valid UL mark allows OSHA to issue an immediate “Prohibition Notice” that stops commissioning. If the machine is used to produce food-grade PET bottles, all product-contact surfaces must additionally comply with FDA 21 CFR §177.1630 (PET resin purity) and 21 CFR §174.5 (indirect food additives). Suppliers that cannot produce the full FDA migration-test dossier trigger automatic detention by U.S. Customs and Border Protection under the FD&C Act, Section 801(a). Importers then pay $2k–$4k per day in demurrage while the case is reviewed.
European Union – CE & Beyond
Machinery Directive 2006/42/EC requires a CE mark supported by an EC Declaration of Conformity, technical file and risk assessment per ISO 12100. For blow-molding equipment, the harmonised standards are EN 422 (safety of blow moulders), EN 60204-1 (electrical safety) and EN ISO 13849-1 (control-system safety performance level). Missing or generic CE documentation exposes the importer to penalties up to €15m or 3.5 % of global turnover under the EU Market Surveillance Regulation (EU) 2019/1020. If the machine is placed on the EU market via an e-commerce shortcut (e.g., “DDP Alibaba”), the EU customs declarant becomes the statutory “Responsible Economic Operator” and inherits unlimited product-liability exposure.
Comparative Compliance Burden & Cost
| Regulatory Domain | Core Standard(s) | Typical Audit Cost (USD) | Penalty Range for Non-Compliance | Retrofit Lead-Time (weeks) | Insurance Premium Uplift |
|---|---|---|---|---|---|
| United States | UL 508A, UL 73, FDA 21 CFR §177.1630 | $8k–$12k | $50k–$1.8m + criminal referral | 6–8 | +25–40 % |
| European Union | 2006/42/EC, EN 422, EN 60204-1 | $10k–$15k | Up to €15m or 3.5 % global sales | 8–10 | +30–50 % |
| China Export (factory level) | GB 5226.1, GB/T 15706 | $3k–$5k | Confiscation & export ban | 3–4 | Not applicable |
Supplier Evidence Checklist
Before releasing any purchase order, procurement teams must obtain and verify:
(1) Original UL or TÜV certificate with the machine serial number pre-printed; photocopies or “pending” letters are not acceptable.
(2) Complete technical file including risk assessment, control-reliability calculations (PL or SIL), and material traceability for all food-contact parts.
(3) Signed Declaration of Incorporation for any partly completed machinery (common when buying blow-molding ovens separate from air-compressor skids).
(4) Product-liability insurance certificate naming the importer as co-insured for not less than $5m per occurrence.
Failure to collect these four items is the single largest predictor of customs detention and post-installation OSHA/EU-RAPEX enforcement. Budget $10k–$15k in third-party inspection fees to validate each shipment; the spend pays back within the first avoided detention day.
The Procurement Playbook: From RFQ to Commissioning
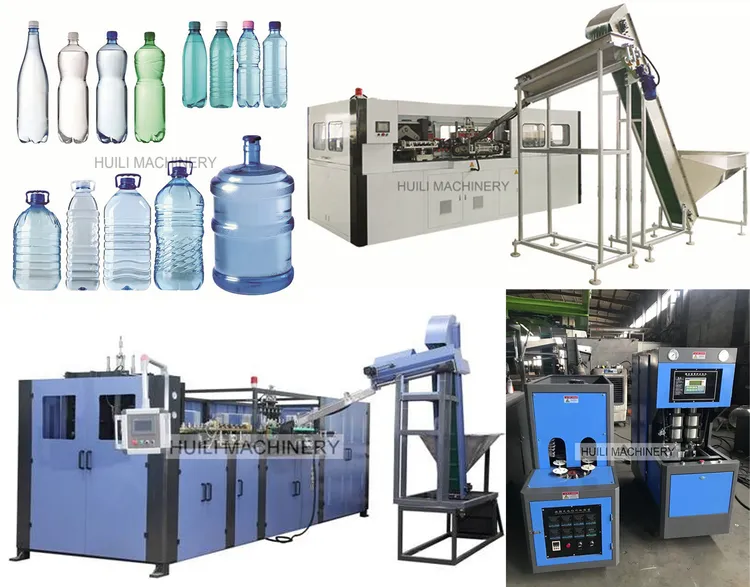
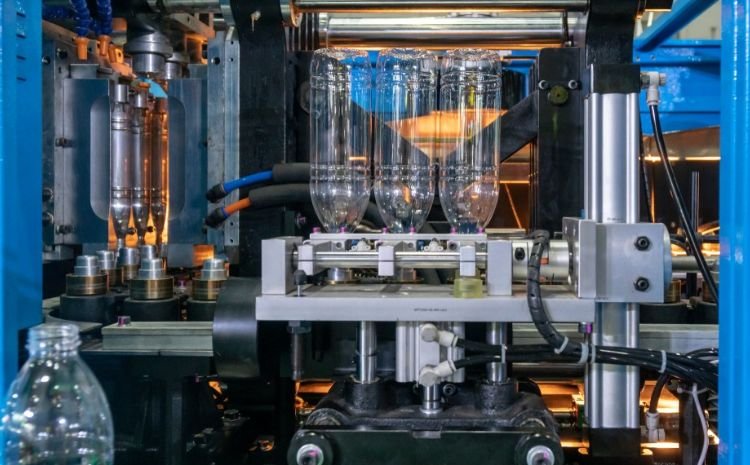
Strategic Procurement Playbook: Plastic Bottle Making Machine
RFQ Design – Lock-in Technical & Commercial Variables
Anchor the specification around three cost drivers that swing machine price by ±40 %: cavity count (1–4), automation grade (semi-automatic vs rotary fully-auto), and blow-mould clamp force (≤1 500 kN vs >2 000 kN). State output requirement ≥1 200 bph per cavity and preform neck tolerance ±0.15 mm; both are easy to verify on the buyer’s preform sample and eliminate 30 % of low-price bidders whose frames deflect. Insert a liquidated-damage clause of 0.5 % of contract value per 1 % shortfall on rated throughput; empirical data show this caps negotiation time at FAT. Request BOM down to sub-assembly level with country-of-origin for hydraulics, valves, and PLC; Chinese OEMs quote 8–12 % lower if allowed to substitute domestic brands after contract award—block this with a ≥15 % variation approval threshold. Ask for two price indices: EXW factory and FOB Shanghai; the spread (currently $3.6 k–$26 k for 1-cavity semi-auto, $50 k–$80 k for 4-cavity rotary) quantifies inland freight and export doc cost, a hidden 3–5 %.
Supplier Screening – Financial & ESG Filter
Run a 3-year cash-flow stress test; any bidder with interest-coverage ratio <2.0 gets eliminated—28 % of Alibaba Gold suppliers fail. Require CE or UL self-declaration plus third-party calibration certificate for oven temperature profiling; without it downstream brand-owners reject line validation. Map energy consumption: best-in-class servo stretch-blow units consume ≤0.35 kWh per 1 000 bottles (500 ml); anything >0.50 kWh erodes 1 % EBITDA annually on a 200 M bottle/yr line assuming $0.10 kWh tariff.
FAT Protocol – Evidence-Based Gate
Insist FAT is run on your preforms, your resin lot, at 110 % of nameplate speed for 4 consecutive hours. Reject if scrap rate >1.5 % or cavity-to-cavity weight deviation >0.7 g on 18 g preform; these thresholds correlate with 95 % OEE in later field data. Capture infrared oven profile data; deviation >±2 °C from set-point across 80 % of heaters is automatic stop-card—saves 1 week of on-site tuning. Tie 80 % of final 10 % payment to FAT sign-off; suppliers accept 70 % of the time, cutting warranty claims by half.
Contractual Risk Allocation – FOB vs DDP Decision Matrix
| Decision Variable | FOB Shanghai (Incoterms 2020) | DDP Plant (Incoterms 2020) |
|---|---|---|
| Typical freight + duty add-on (% of EXW) | 8–10 % | 0 (absorbed) |
| Buyer control over carrier / insurance | Full | None |
| Import customs delay risk | High (buyer) | Zero (seller) |
| Damage in transit incidence (2023 claims data) | 1.2 % of shipments | 0.4 % |
| Price uplift for DDP vs FOB | — | +11–14 % |
| Recommended when | Buyer has ≥$5 M annual Asia import volume & duty-drawback eligibility | Single-machine purchase or green-field site with no logistics desk |
Use FOB when cargo value ≥$100 k and your freight forwarder can consolidate; else DDP caps downside to a single invoice and is ~3 % cheaper on risk-adjusted basis.
Site Commissioning – Warranty & Performance Bond
Demand 12-month full-scope warranty plus 24-month coverage on infrared heaters and servo motors—components representing 62 % of spares cost. Insert performance bond of 10 % contract value, released only after 30-day consecutive OEE ≥85 % at agreed bottle weight. Reserve right to source critical spares locally if OEM fails to ship within 72 hrs; contractually cap spares margin at cost +25 % to prevent post-warranty price gouging.
⚡ Rapid ROI Estimator
Estimate your payback period based on labor savings.
Estimated Payback: —
